Non-lapsing SMSF Binding Death Benefit Agreement
$450 includes GST
Control who receives your super when you die. Includes your SMSF Deed update and supporting legal documents.
Your SMSF Binding Death Benefit Agreement directs the trustee to pay your superannuation to the people you nominate when you die.
Your SMSF holds a substantial part of your family’s wealth. Your Will does not automatically control that money. Without an effective binding direction, the fund’s rules and the trustee’s discretion determine who receives it. A second spouse, children from an earlier relationship and the people controlling the fund all have something to fight over.
Legal Consolidated’s non-lapsing Binding Death Benefit Agreement puts your directions in place before that fight begins. It binds the trustee under your fund’s rules and has no automatic three-year expiry. Your SMSF Deed is updated at the same time, so the rules and Agreement work together.
A nomination form is only part of the protection. The SMSF Deed must support it. The recipient descriptions, signing requirements and directions to the trustee must align. An inconsistent clause gives a disappointed beneficiary a weapon.
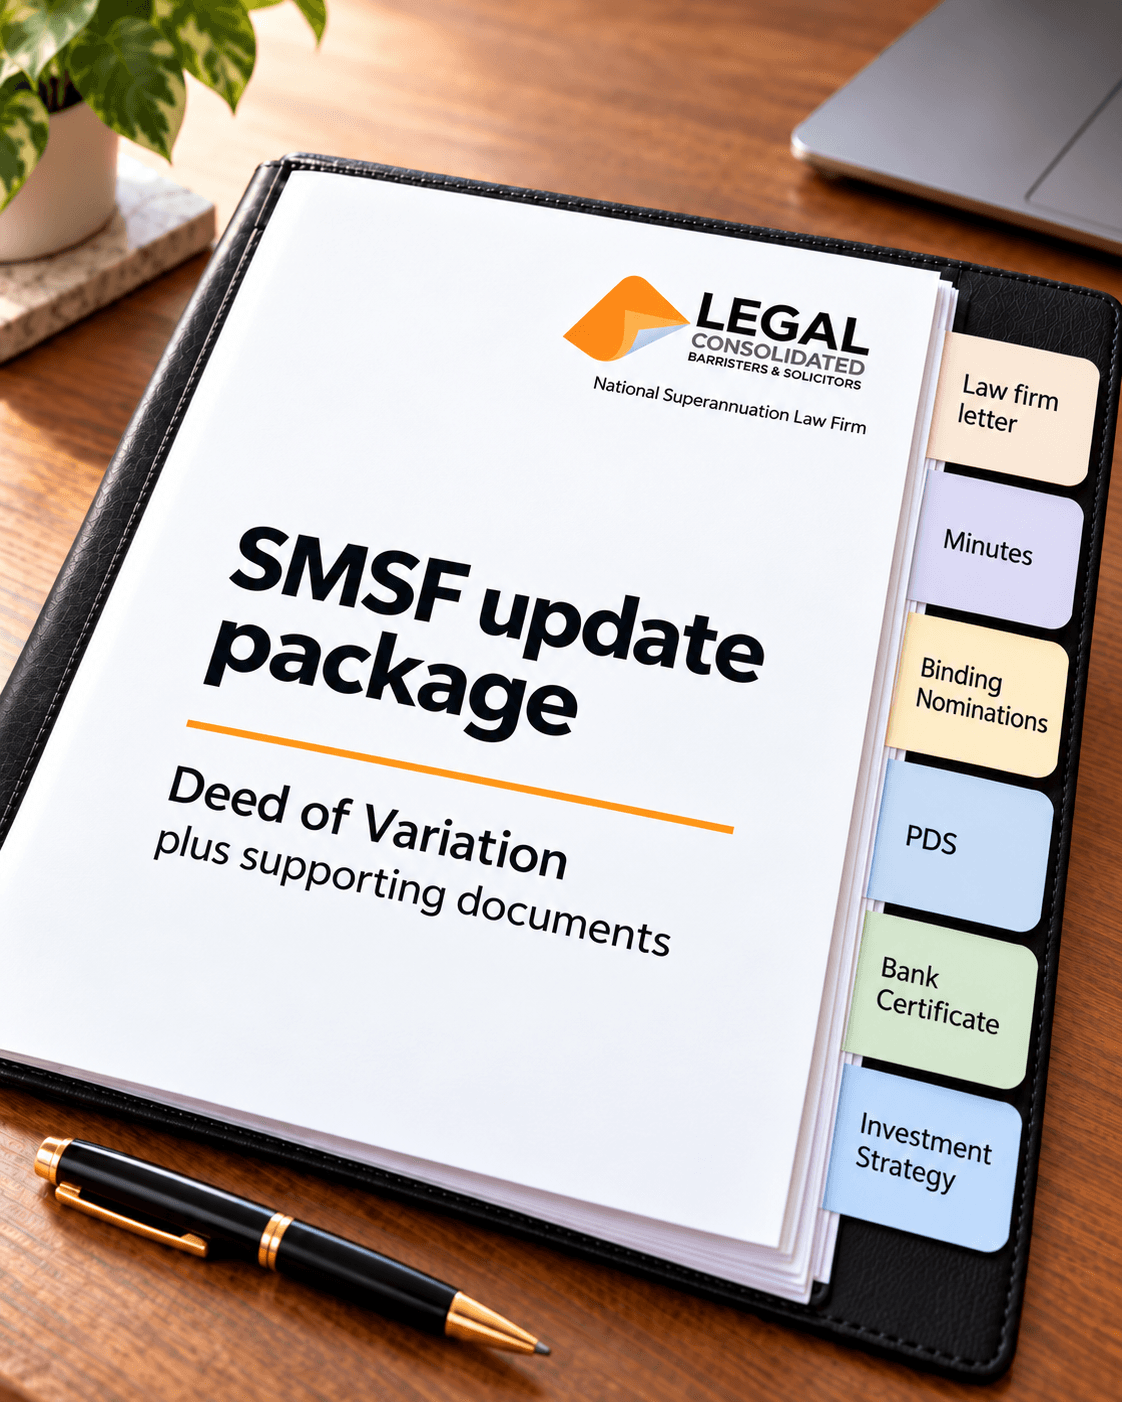
Our SMSF Update brings the governing rules and death benefit Agreement together in one coordinated package. To keep everything in order, you also confirm the trustees and members as you build. Change them at no extra charge if you wish.
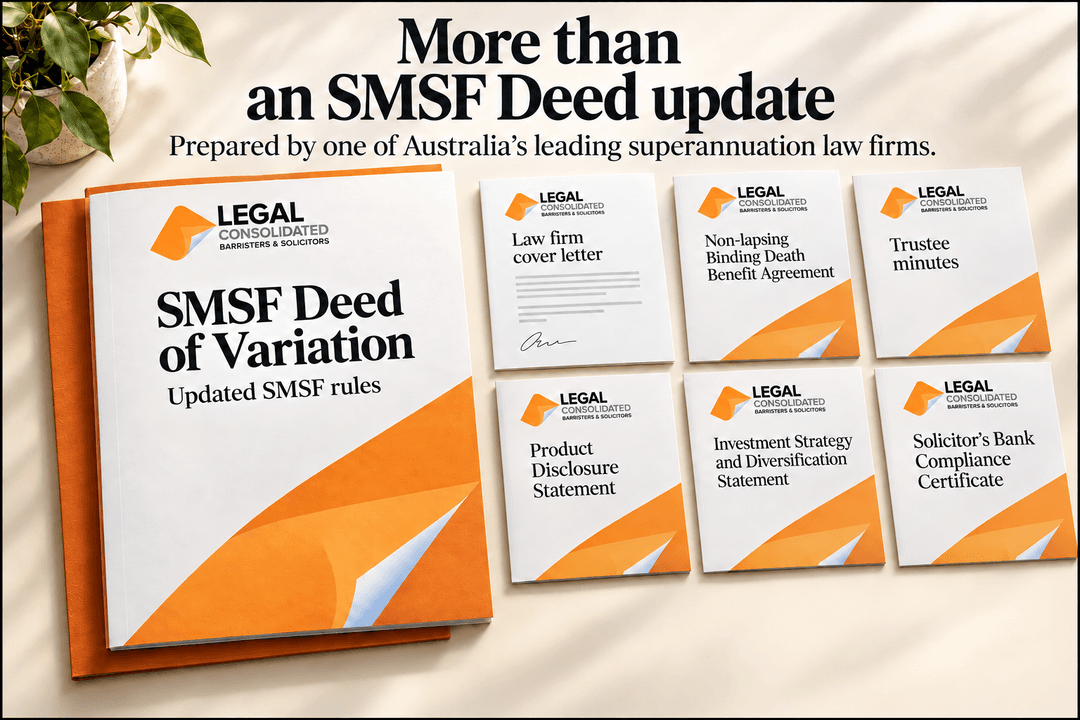
One complete SMSF Update package. You also confirm your trustees and members, or change them at no extra charge.
Legal Consolidated’s signed law firm cover letter confirms that we authored your documents and take responsibility for them. Read the free sample before building.
Legal Consolidated is a national Australian law firm serving Western Australia, Northern Territory, South Australia, Queensland, New South Wales, Victoria, Tasmania and the Australian Capital Territory. You build directly with the law firm responsible for your documents. Your accountant and financial planner remain your trusted advisers on the strategy.
A non-binding nomination tells the trustee what you want. A valid binding nomination directs the trustee what to do. Legal Consolidated’s non-lapsing Agreement removes the need to renew your direction simply because three years have passed.
Non-lapsing does not mean ‘sign and forget’. Review your directions after marriage, separation, a death or a change in your family’s needs. The recipients must remain eligible under superannuation law, and the Agreement must continue to satisfy your fund’s rules.
Dad dies. His daughter challenges the direction that his SMSF benefits go to his partner. She argues that the nomination fails because it does not satisfy the statutory nomination standards, including the three-year rule.
In Hill v Zuda Pty Ltd [2022] HCA 21, the High Court unanimously rejected the appeal. Regulation 6.17A of the Superannuation Industry (Supervision) Regulations 1994 (Cth) does not apply to SMSFs. The fund’s own rules remain critical.
Legal Consolidated carefully crafts the deed and Agreement to provide a non-lapsing direction. The protection sits in the coordinated documents and their proper completion.
A father plans for his wife and two daughters. His death benefit nomination directs payment to the ‘Trustee of Deceased Estate’. The family ends up in court arguing over those words.
In Munro v Munro [2015] QSC 61, the nomination failed. It did not nominate a dependant or the father’s legal personal representative as required by the deed and superannuation law. His Will did not repair the nomination.
Legal Consolidated’s Agreement uses the recipient descriptions and legal machinery that work with the updated deed. If your strategy sends superannuation into your estate, the Agreement nominates your legal personal representative — the executor or administrator who administers your estate.
Dad directs his SMSF benefits to his daughters. After he dies, his second wife takes control of the corporate trustee and allocates the benefits to herself. The daughters have to fight for their father’s money.
In Wooster v Morris [2013] VSC 594, the nomination was declared binding on both the former trustees and the replacement company trustee. The daughters obtained orders enforcing their entitlement. The dispute shows why signing, delivery and the fund’s records deserve the same care as the words on the page.
Follow our law firm’s instructions and keep the signed Agreement with your SMSF records. That evidence strengthens the direction when someone later questions it.
Your direction nominates one or more eligible superannuation dependants, your legal personal representative, or a combination of them. Superannuation dependants include a spouse or de facto partner, children of any age, a person financially dependent on you, and a person in an interdependency relationship with you. An interdependency relationship involves a close personal relationship and the support requirements set by superannuation law.
The rules for receiving a death benefit and the rules for receiving it tax-free are different. An adult child is an eligible superannuation dependant, but that does not automatically make the child a death benefits dependant for tax purposes.
Directing superannuation to your legal personal representative brings it into your estate for administration under your Will. Legal Consolidated’s 3-Generation Testamentary Trust Will provides Divorce Protection Trusts, Bankruptcy Trusts, Age of Majority provisions and trustee control mechanisms for the inheritance.
Your accountant and financial planner assess the tax cost and the best payment strategy for your family. Read our explanation of superannuation death tax and Superannuation Testamentary Trusts. A nomination controls payment directions; it does not by itself make a taxable benefit tax-free.
A valid reversionary pension provides for a pension to continue to an eligible beneficiary after you die. Your death benefit Agreement deals with benefits covered by its terms. Align the two so your pension instructions and death benefit directions work together.
The Reversionary Pension Kit is a separate document. Your financial planner and accountant help settle the pension and estate planning strategy before you complete the directions.
Have your fund’s name, address, original deed date, trustee details and member details ready. Download the editable Word checklist and work through it with your accountant, lawyer or financial planner.
Start the free building process on our law firm’s website. Work through the fund, trustee and member questions at your own pace. Read the hints and watch the training videos as you go. You pay when you are ready to buy the completed documents.
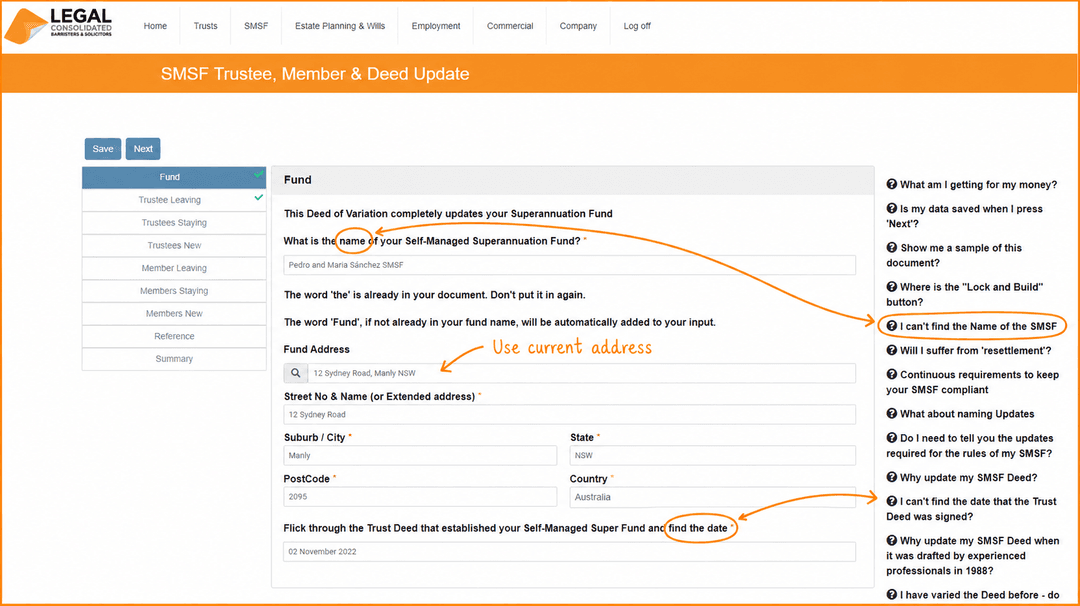
Read the hints beside the questions as you build your SMSF Update.
Select ‘Lock and Build’ when your answers are ready. Pay and download the SMSF Update and our law firm cover letter. Complete the death benefit Agreement for each member who wants a direction and follow the signing and delivery instructions.
Keep the signed deed update, Agreement and supporting documents with your original deed and previous variations. Your nomination and fund records then sit together, ready to support your wishes.
Need help with a question? Start building and read the hints, then telephone 1800 141 612. We help you work through your answers.
A well-drafted Agreement needs proper completion. Follow our instructions for signatures, witnesses, delivery to the trustee and keeping the original. Do not backdate documents or ask someone to witness a signature they did not see.
SMSFs follow their own governing rules as well as superannuation law. The High Court’s decision in Hill v Zuda does not excuse ignoring the requirements in your deed. Your signed documents and delivery records help answer a challenge years later.
Two stepsons held back from claiming against their mother’s estate after their stepfather promised them his superannuation. He later left them out. In Lucas v Salman [2022] NSWSC 1301, their contract claim failed, but their estoppel claim succeeded. Estoppel prevents a person from departing from a promise after another person has relied on it to their detriment. The Court awarded the stepsons the value of the superannuation, plus interest.
Keep estate planning promises, your Will and your superannuation directions aligned. Tell your advisers about commitments made to family members.
Dr Nespolon signed his SMSF nomination in hospital on the day he died. His partner then had to fight the trustee for benefits worth about $4.7 million. In van Camp v Bellahealth Pty Ltd [2024] NSWSC 7, the Court upheld the nomination and rejected the capacity and unconscionable conduct challenges.
The evidence included the records of doctors and advisers. Put your directions in place while well and keep evidence of your instructions and understanding.
A member’s message to his sister said his partner should receive nothing. The dispute concerned whether the de facto relationship had ended under the fund’s nomination rules. In Nguyen v Australian Financial Complaints Authority [2024] FCAFC 77, the partner’s appeal succeeded. The Full Federal Court rejected the conclusion that the message established the relationship had ended.
This was a public offer fund, not an SMSF. Its lesson remains practical: review and formally update your directions when relationships change.
Webb v Teeling [2009] FCA 1094 concerned a public offer fund’s payment decision and a dependant who died before payment. The Court upheld the Tribunal’s decision against payment to that dependant’s estate. The outcome depended on the fund’s rules and the Tribunal’s fair and reasonable assessment.
Do not assume that surviving a member automatically secures payment to a recipient’s estate. Review substitute recipients and the option of payment to your legal personal representative with your advisers.
Loss of capacity adds another layer. Re Narumon Pty Ltd [2018] QSC 185 examines attorneys, pension and death benefit arrangements. Get the directions and your Enduring Power of Attorney coordinated before capacity becomes an issue.
Legal Consolidated’s SMSF Deed Update is carefully crafted to update the rules of your existing fund without transferring its assets. Your fund keeps its assets while its governing rules are brought up to date. The Northern Territory has a separate nominal duty and lodgement requirement, explained below.
This guidance concerns the rules update itself. A separate transfer of fund property, declaration of trust over property or change to ownership interests needs its own duty review. If you change trustees, also check the duty and title-registration requirements for the fund’s assets.
A deed updating an SMSF’s rules is subject to Northern Territory stamp duty where the NT duty laws apply. This includes a deed executed in the NT, or a deed relating to NT property or a matter or thing done or to be done in the NT, even if signed elsewhere.
For a trust deed that is not otherwise chargeable with duty based on the value of property, the nominal duty is $20, plus $5 for each duplicate or counterpart. Lodge the deed and the required Stamp Duty Lodgement Form with the Territory Revenue Office within 60 days after the deed is first executed. Duty must also be paid within that period unless the assessment specifies a later payment date.
Postal address: Territory Revenue Office, GPO Box 1974, Darwin NT 0801. Obtain the current form from the NT Department of Treasury and Finance.
See Stamp Duty Act 1978 (NT) s 9, s 9B and sch 1 item 2.
Legal Consolidated’s rules update for a complying SMSF does not attract NSW transfer duty and does not need to be lodged with Revenue NSW for endorsement. The exemption for instruments relating to superannuation is in the Duties Act 1997 (NSW) s 65(10)(a).
A separate purchase or transfer of property is assessed under its own duty rules. The exemption for the SMSF deed does not remove those requirements.
An instrument amending the provisions governing a complying superannuation fund is exempt from Victorian duty under the Duties Act 2000 (Vic) s 39. The exemption also covers a fund that, in the trustees’ opinion, will become a complying superannuation fund within 12 months after execution.
A Legal Consolidated SMSF Deed Update satisfying those requirements does not require stamping merely because it updates the fund’s rules. Separate property transfers have their own duty requirements.
A Legal Consolidated SMSF Deed Update that varies only the fund’s general terms and conditions does not attract Queensland transfer duty and does not require stamping. Queensland Revenue Office expressly confirms this treatment for variations confined to general trust terms.
A cash contribution or cash benefit payment does not, by itself, attract Queensland transfer duty. A separate transaction involving dutiable property, such as Queensland land, requires its own assessment of duty, exemptions and concessions.
See Duties Act 2001 (Qld) ss 8–10 and the Queensland Revenue Office guidance on trusts.
A Legal Consolidated SMSF Deed Update confined to updating the fund’s governing rules, without a dutiable transaction, does not attract WA transfer duty or require lodgement for stamping.
RevenueWA’s superannuation guidance distinguishes the fund deed and its amendments from a duty-endorsed property acquisition or declaration of trust. It requests stamped copies of fund deeds and amendments where they are dated before 1 July 2008.
A separate transfer of dutiable property or declaration of trust over that property has its own duty and lodgement requirements. See Duties Act 2008 (WA) ss 11 and 23 and RevenueWA’s superannuation duty requirements.
Legal Consolidated’s SMSF Update is carefully crafted to update the fund’s governing rules without transferring its assets. A rules-only variation that does not create or vary beneficial interests in trust property is covered by the Stamp Duties Act 1923 (SA) s 71(5)(i), where the original trust instrument is duly stamped. General exemption 30 in sch 2 pt 2 also covers deeds for which no specific charge or basis for charging duty is fixed.
A rules-only update satisfying the applicable exemption does not require lodgement for duty assessment. A separate arrangement that transfers property or creates or varies beneficial interests in South Australian property needs its own duty review before signing.
A Legal Consolidated SMSF Deed Update confined to the fund’s governing rules does not attract ACT conveyance duty or require duty lodgement merely because the rules are updated. The applicable legislation is the current Duties Act 1999 (ACT), ch 2.
A separate transfer of dutiable property or declaration of trust over that property has its own duty requirements.
Superannuation trust deeds and variations dated on or after 1 July 2017 do not require stamping in Tasmania. This applies to a Legal Consolidated SMSF Deed Update signed on or after that date.
Historical deeds dated before 1 July 2017 have different stamping requirements. A separate transaction involving dutiable property also needs its own duty review. See the State Revenue Office Tasmania guidance, paragraph 1.3.
Practical legal strategies from a national tax and superannuation law firm.
Join PRUDENCE