-
SMSF Trustee
-
$450 includes GST
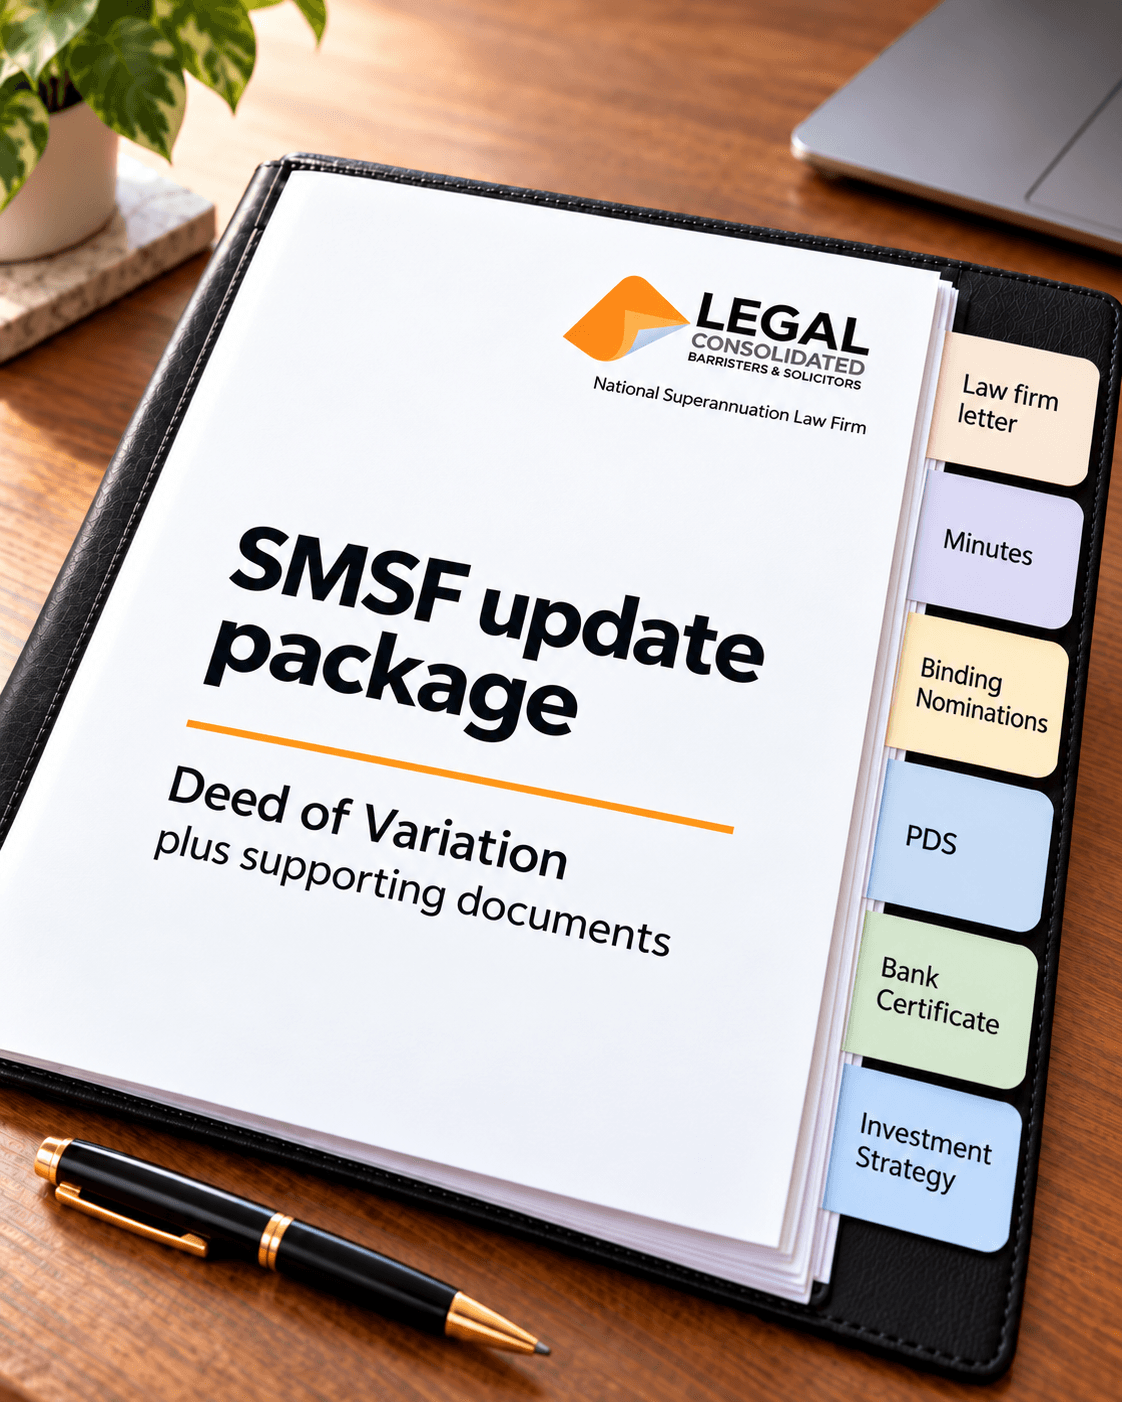
Change your SMSF trustee. Includes deed update, Death Benefit Agreement, minutes, Product Disclosure Statement and Bank Compliance Certificate on law firm letterhead.
Changing an SMSF trustee changes who looks after your retirement savings. The appointment power, signatures and fund records work together.
Legal Consolidated handles the trustee change through the complete SMSF Update. The package updates the governing rules, changes trustees, confirms or changes the members, and supplies the supporting documents. Press the above START BUILDING FOR FREE button to build your SMSF Deed Update.
One complete SMSF Update package. You also confirm your trustees and members, or change them at no extra charge.
Your accountant and financial planner shape the strategy. Our legal documents provide the machinery to put it into effect. See everything included in the SMSF Update.
You have two choices in your SMSF:
See Superannuation Industry (Supervision) Act 1993 (Cth) s 17A.
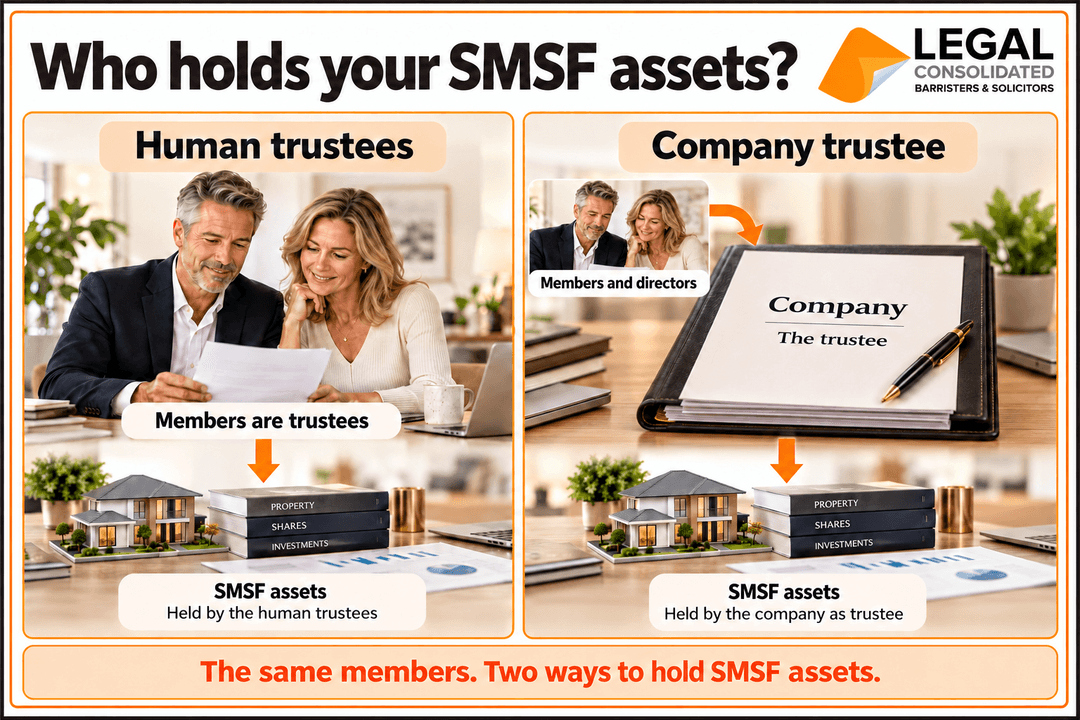
The same members. Two ways to hold SMSF assets.
If you need a company, build a Special Purpose SMSF Company. You do this first. Then finish building the SMSF Deed.
Keep your original SMSF deed, later variations and current fund records beside you. Download the editable Word checklist to gather the details before you start. Accountants, advisers and lawyers are welcome to replace our logo with their own.
Enter the fund name, current address and date of the original deed. Then work through the trustees and members leaving, staying or joining. Read the free hints and watch the training videos as you answer the questions. For help answering a question, telephone 1800 141 612.
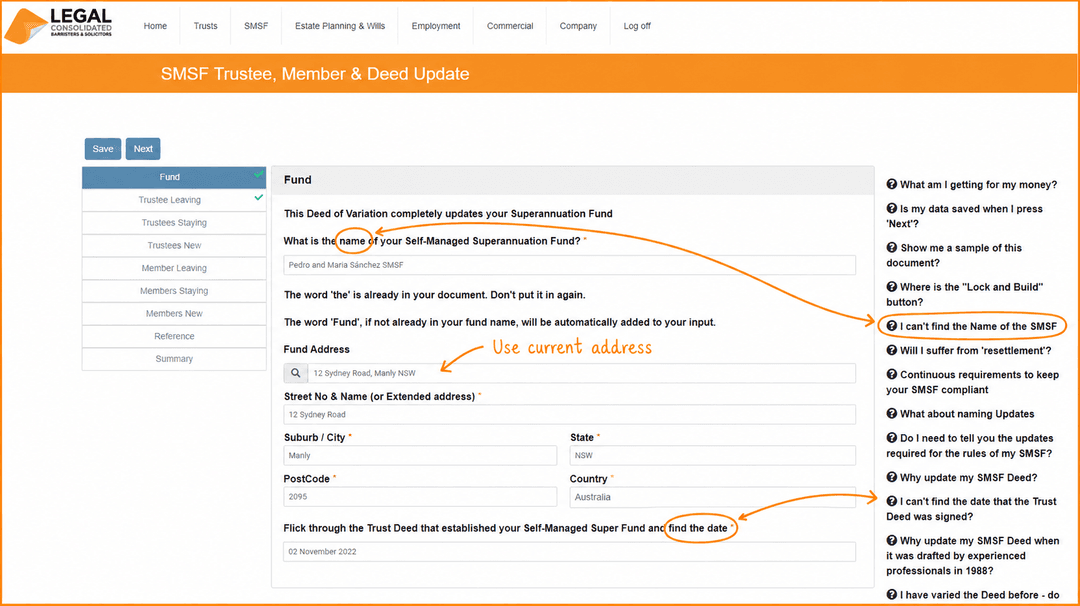
The hints beside the questions help you find the fund name and original deed date.
Work through the questions for free. When you are ready to buy, select Lock and Build and complete payment. Download your finished legal documents and follow Legal Consolidated’s cover letter and signing instructions.
Your SMSF Update and supporting documents are ready to download.
After Mr Hayne died, his partner sought to replace the company trustee with a company she controlled alone. His daughter challenged the change. Control over the fund’s death benefits was at stake.
In Moss Super Pty Ltd v Hayne [2008] VSC 158, the existing company also held the separate office of founder. The documents did not exercise the founder’s power to appoint. The resignation took effect, but the replacement appointment failed. The fund was left without a validly appointed trustee.
The lesson: identify every office and exercise the correct power. The right person signing in the wrong capacity is not enough.
A father replaced his daughter as trustee with his de facto partner. After he died, the daughter challenged the trustee changes and his binding death benefit nomination in Perry v Nicholson [2017] QSC 163.
The Court held that the signed minutes satisfied this deed’s written removal and appointment requirements. The judgment left the nomination’s delivery to the trustees for further argument. It did not finally decide that the partner received the death benefit.
The lesson: the deed’s actual requirements matter. This decision does not justify relying on minutes for every fund. Legal Consolidated documents the trustee change through the SMSF Update’s Deed of Variation and supporting records.
In McCabe as Syndic for the Victor Chang Cardiac Research Institute Ltd (ACN 068 363 235) v The Baltins Superannuation Fund [2017] NSWSC 1671, the sole member died and the corporate trustee was deregistered. About $1.2 million in fund assets was caught in the resulting problem.
The rules gave members the power to appoint trustees but ended membership on death. They provided no power for the dead member’s legal personal representative to replace them. The Court appointed new trustees and ordered that the fund property vest in them.
The lesson: keep the trustee company registered and put succession machinery in place before death. An online update does not replace the reinstatement or court process required after a trustee company is deregistered.
The signed deed is the foundation. Finish the implementation so the ATO, bank, investment providers and auditor recognise the same trustee structure.
The online building process prepares the legal documents. It does not lodge ATO or ASIC notifications, change bank mandates or transfer registered asset titles for you.
No. The ATO reviews new trustees and members only when it has a reason to. A trustee change does not automatically mean the fund has become non-complying.
If Super Fund Lookup shows ‘Regulation details withheld’, ask your authorised contact or tax agent to resolve it with the ATO. Official guidance advises against contributions and rollovers while those details are withheld. It also distinguishes newly established funds, for which that status alone should not prevent opening a bank account, subject to the bank’s requirements. See Super Fund Lookup’s explanation of SMSF status.
The SMSF Update continues your existing fund. Changing the trustee is different from moving assets into another fund or changing who benefits from them.
Separate duty, evidence and title-registration requirements apply when assets such as land move into the new trustee’s name. The outcome depends on the property, jurisdiction and transaction. Confirm the applicable exemption or concession and any lodgement requirements before transferring title. Revenue NSW publishes evidence requirements for SMSF trustee transfers. Do not treat a deed update as a blanket exemption for every associated transfer.
Legal Consolidated’s SMSF Deed Update is carefully crafted to update the rules of your existing fund without transferring its assets. Your fund keeps its assets while its governing rules are brought up to date. The Northern Territory has a separate nominal duty and lodgement requirement, explained below.
This guidance concerns the rules update itself. A separate transfer of fund property, declaration of trust over property or change to ownership interests needs its own duty review. If you change trustees, also check the duty and title-registration requirements for the fund’s assets.
A deed updating an SMSF’s rules is subject to Northern Territory stamp duty where the NT duty laws apply. This includes a deed executed in the NT, or a deed relating to NT property or a matter or thing done or to be done in the NT, even if signed elsewhere.
For a trust deed that is not otherwise chargeable with duty based on the value of property, the nominal duty is $20, plus $5 for each duplicate or counterpart. Lodge the deed and the required Stamp Duty Lodgement Form with the Territory Revenue Office within 60 days after the deed is first executed. Duty must also be paid within that period unless the assessment specifies a later payment date.
Postal address: Territory Revenue Office, GPO Box 1974, Darwin NT 0801. Obtain the current form from the NT Department of Treasury and Finance.
See Stamp Duty Act 1978 (NT) s 9, s 9B and sch 1 item 2.
Legal Consolidated’s rules update for a complying SMSF does not attract NSW transfer duty and does not need to be lodged with Revenue NSW for endorsement. The exemption for instruments relating to superannuation is in the Duties Act 1997 (NSW) s 65(10)(a).
A separate purchase or transfer of property is assessed under its own duty rules. The exemption for the SMSF deed does not remove those requirements.
An instrument amending the provisions governing a complying superannuation fund is exempt from Victorian duty under the Duties Act 2000 (Vic) s 39. The exemption also covers a fund that, in the trustees’ opinion, will become a complying superannuation fund within 12 months after execution.
A Legal Consolidated SMSF Deed Update satisfying those requirements does not require stamping merely because it updates the fund’s rules. Separate property transfers have their own duty requirements.
A Legal Consolidated SMSF Deed Update that varies only the fund’s general terms and conditions does not attract Queensland transfer duty and does not require stamping. Queensland Revenue Office expressly confirms this treatment for variations confined to general trust terms.
A cash contribution or cash benefit payment does not, by itself, attract Queensland transfer duty. A separate transaction involving dutiable property, such as Queensland land, requires its own assessment of duty, exemptions and concessions.
See Duties Act 2001 (Qld) ss 8–10 and the Queensland Revenue Office guidance on trusts.
A Legal Consolidated SMSF Deed Update confined to updating the fund’s governing rules, without a dutiable transaction, does not attract WA transfer duty or require lodgement for stamping.
RevenueWA’s superannuation guidance distinguishes the fund deed and its amendments from a duty-endorsed property acquisition or declaration of trust. It requests stamped copies of fund deeds and amendments where they are dated before 1 July 2008.
A separate transfer of dutiable property or declaration of trust over that property has its own duty and lodgement requirements. See Duties Act 2008 (WA) ss 11 and 23 and RevenueWA’s superannuation duty requirements.
Legal Consolidated’s SMSF Update is carefully crafted to update the fund’s governing rules without transferring its assets. A rules-only variation that does not create or vary beneficial interests in trust property is covered by the Stamp Duties Act 1923 (SA) s 71(5)(i), where the original trust instrument is duly stamped. General exemption 30 in sch 2 pt 2 also covers deeds for which no specific charge or basis for charging duty is fixed.
A rules-only update satisfying the applicable exemption does not require lodgement for duty assessment. A separate arrangement that transfers property or creates or varies beneficial interests in South Australian property needs its own duty review before signing.
A Legal Consolidated SMSF Deed Update confined to the fund’s governing rules does not attract ACT conveyance duty or require duty lodgement merely because the rules are updated. The applicable legislation is the current Duties Act 1999 (ACT), ch 2.
A separate transfer of dutiable property or declaration of trust over that property has its own duty requirements.
Superannuation trust deeds and variations dated on or after 1 July 2017 do not require stamping in Tasmania. This applies to a Legal Consolidated SMSF Deed Update signed on or after that date.
Historical deeds dated before 1 July 2017 have different stamping requirements. A separate transaction involving dutiable property also needs its own duty review. See the State Revenue Office Tasmania guidance, paragraph 1.3.
Yes. The complete SMSF Update replaces the governing rules and confirms or changes trustees and members. It also provides the supporting documents described above. Your trustee change, governing rules and supporting documents are prepared together in one coordinated package.
No. A company with a new name and the same ACN remains the same legal entity. Its property, rights and obligations continue under Corporations Act 2001 (Cth) s 161. Keep ASIC’s name-change certificate and update the fund, bank and investment records. Do not enter the same company as an outgoing and incoming trustee merely because its name changed.
Identify who holds the appointment power under the deed and who is legally authorised to act. An executor or administrator, or an attorney under an enduring power of attorney, has a distinct legal role. That role does not automatically appoint the person as SMSF trustee or company director.
Check the deed, company constitution and the statutory exceptions and timing rules before changing the structure. Contact us if the person needed to sign has died, lacks capacity or is disqualified. Do not sign that person’s name or assume another family member inherits the office.
Obtain advice about reinstatement, appointment powers and the fund’s assets before using the ordinary update process. A deregistered company has ceased to exist. Entering its name in a new deed does not restore it. The McCabe case above shows why court orders are required where the deed provides no workable appointment route.
Coordinate the trustee or director appointment with admission as a member so the fund meets the SMSF rules. There is no single sequence that overrides every deed and statutory exception. Your accountant and financial planner help coordinate the transaction; follow the legal documents’ appointment and signing steps.
Use the standalone Checklist button above to gather the fund, trustee and member details. The free sample shows the SMSF Update documents. Then start the free building process. The questions, hints and training videos explain the information required as you work through the update.
Legal Consolidated authors the documents and accepts responsibility through its law firm cover letter. We are a national Australian law firm serving Western Australia, the Northern Territory, South Australia, Queensland, New South Wales, Victoria, Tasmania and the Australian Capital Territory. A non-law firm template reseller does not provide that law firm responsibility.
Start with your original deed, later variations and current fund records beside you. For help answering the questions, telephone 1800 141 612. No payment is required to work through the questions; payment is required when you choose to buy the documents.
Practical legal strategies from a national tax and superannuation law firm.
Join PRUDENCE