-
SMSF Trustee, Member and Deed Update
-
$450 includes GST
Includes deed update, Death Benefit Agreement, minutes, Product Disclosure Statement and Bank Compliance Certificate on law firm letterhead.
Your SMSF holds your retirement savings. But does your SMSF deed legally protect you and your family?
An outdated deed is litigation bait. Your trustee lacks the power to make the desired investment. The ATO questions money arriving in your super fund. A distant family member challenges who gets your super when you die.
Legal Consolidated has found that many brand-new SMSF deeds fail to protect you.
Our SMSF Update provides a complete package of legal documents to strengthen your fund and protect your decisions. It updates the governing rules, strengthens control over death benefits, supports investment and pension strategies, and provides the records your accountant, financial planner and auditor need.
These trusted advisers report back on SMSF auditors and the Australian Taxation Office. They tell us what auditors question, what documents the ATO requests during desktop audits, and best practices for drafting SMSF documents.
Our lawyers monitor court decisions, superannuation legislation, ATO requirements and State Revenue Office practices across Australia.
We bring that legal knowledge and practical experience together in the SMSF Update.
Your SMSF Update protects your retirement savings, strengthens trustee control, and provides the records your accountant, financial planner, and SMSF auditor need. The suite of documents includes:
One complete SMSF Update package. You also confirm your trustees and members, or change them at no extra charge.
The SMSF Update package includes: cover letter, Deed of Variation, Solicitor's Bank Certificate, Investment and Diversification Strategy and PDS.
Do not allow distant relatives and the trustee to decide who gets your super when you die. You can enter into an Agreement with your Superannuation fund before you die. This Agreement is called a non-lapsing Binding Death Benefit Agreement. It directs your SMSF trustee to pay your superannuation to the people you want. Our Agreement binds the trustee, whoever it may be, and never expires. It also helps reduce the 32% death tax on your superannuation.
Your SMSF Update confirms your existing trustees and members. It also allows you to change them if you wish.
Family relationships change. A member who once agreed with your decisions later challenges them. Our Product Disclosure Statement records members' rights, responsibilities and risks. Uniquely, it protects you, your accountant and auditor.
Your SMSF auditor carefully examines how you invest your retirement savings. If the ATO does not like you, the first thing it does in a desktop audit is compare your Investment Strategy and Diversification Statement with your past behaviour.
Your package includes an Investment Strategy and Diversification Statement, which allows you maximum protection in dealing with the ATO's demands. These documents carefully and correctly document the trustee's investment decisions and the reasons behind them.
Your trustee minutes record the decision to update the SMSF deed and supporting documents. They establish who approved the update and when.
Our minutes reduce disputes and strengthen your position when an SMSF auditor or the ATO examines the SMSF.
At times your SMSF may want or need to borrow money. Your bank requires a lawyer-prepared certificate to confirm that the SMSF deed gives the trustee the necessary borrowing and security powers.
At no additional charge, Legal Consolidated provide the solicitor's Bank Compliance Certificate. It is presented on our law firm's letterhead.
Legal Consolidated authors your SMSF Update and supporting legal documents.
You receive our signed law firm cover letter confirming that responsibility. It also explains how to sign, store and implement your documents.
You are dealing directly with the Australian law firm preparing your documents — not a website reselling another lawyer's templates.
Your SMSF Update preserves existing pensions, accrued benefits, death benefit directions, borrowing arrangements and historical concessions.
Your existing fund continues. The update strengthens its governing rules without requiring you to start a new SMSF.
Dad dies. His daughter is unhappy that Dad's superannuation goes to his sexual partner. She wants to overturn the SMSF death benefit arrangement.
In Hill v Zuda Pty Ltd [2022] HCA 21, the daughter argued that the law states that death benefit agreements automatically expire 3 years after signing.
The dispute reached the High Court. The daughter lost. The Court confirmed that those statutory witnessing and three-year expiry requirements did not apply to certain SMSFs. Legal Consolidated's SMSF Deeds are drafted so the binding nomination of who gets your super when you die never expires.
But another family was not so fortunate.
In Munro v Munro [2015] QSC 61, a father wanted his superannuation paid to his Will. His nomination said ‘Trustee of Deceased Estate’. His SMSF deed required ‘legal personal representative’. The SMSF deed and supporting documents conflicted.
The Supreme Court of Queensland held that the nomination was not binding. The father's wishes were overridden.
Two SMSFs. Two bitter family disputes. Two different outcomes. Legal Consolidated's SMSF Update includes a non-lapsing Binding Death Benefit Agreement and a Deed of Variation drafted to work together. The documents put protective machinery in place before your family has a reason to fight.
Check for these weaknesses:
Your accountant and financial planner help shape the strategy. The deed gives the trustee the legal machinery to carry it out.
Start the free, educational building process. No payment is required until you Lock and Build and wish to buy the documents.
Our free online questions guide you through the building process.
The questions have hints and training videos. Your accountant, lawyer or financial planner can help you complete the questions.
For free help answering the questions, telephone us to speak to a specialist SMSF lawyer. We can also discuss your answers. But start the building process first, as it answers most questions.
When you are satisfied with your answers, press Lock and Build. Enter your credit card details. Within two minutes, we email you the finished legal documents. You can also view your documents on our website anytime.
Download and print your documents, follow our law firm's signing instructions, and keep the signed originals with your SMSF records.
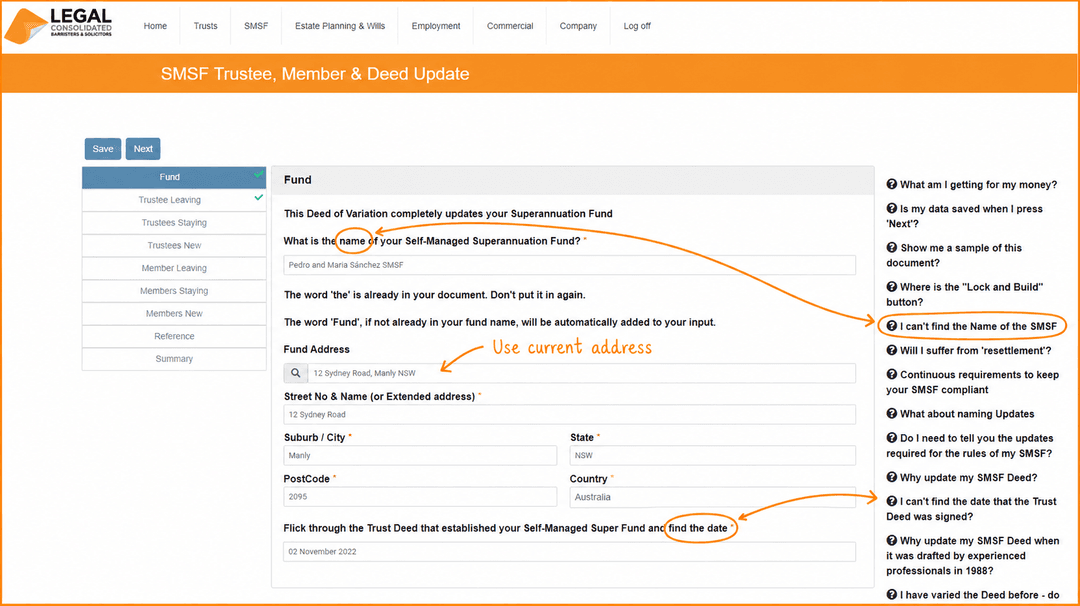
The free building process educates you as you build the SMSF Update.
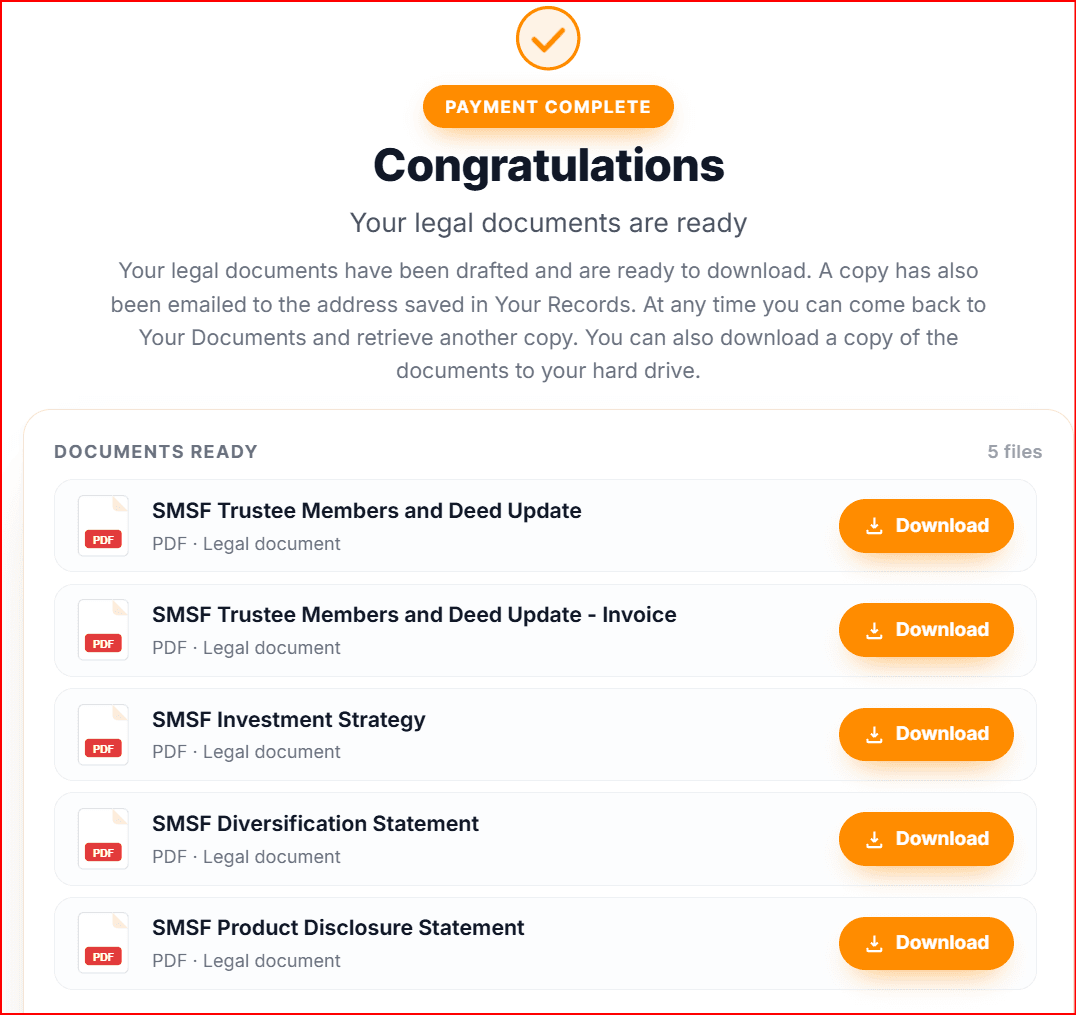
Your completed SMSF Update documents are ready to download.
Legal Consolidated’s SMSF Deed Update is carefully crafted to update the rules of your existing fund without transferring its assets. Your fund keeps its assets while its governing rules are brought up to date. The Northern Territory has a separate nominal duty and lodgement requirement, explained below.
This guidance concerns the rules update itself. A separate transfer of fund property, declaration of trust over property or change to ownership interests needs its own duty review. If you change trustees, also check the duty and title-registration requirements for the fund’s assets.
A deed updating an SMSF’s rules is subject to Northern Territory stamp duty where the NT duty laws apply. This includes a deed executed in the NT, or a deed relating to NT property or a matter or thing done or to be done in the NT, even if signed elsewhere.
For a trust deed that is not otherwise chargeable with duty based on the value of property, the nominal duty is $20, plus $5 for each duplicate or counterpart. Lodge the deed and the required Stamp Duty Lodgement Form with the Territory Revenue Office within 60 days after the deed is first executed. Duty must also be paid within that period unless the assessment specifies a later payment date.
Postal address: Territory Revenue Office, GPO Box 1974, Darwin NT 0801. Obtain the current form from the NT Department of Treasury and Finance.
See Stamp Duty Act 1978 (NT) s 9, s 9B and sch 1 item 2.
Legal Consolidated’s rules update for a complying SMSF does not attract NSW transfer duty and does not need to be lodged with Revenue NSW for endorsement. The exemption for instruments relating to superannuation is in the Duties Act 1997 (NSW) s 65(10)(a).
A separate purchase or transfer of property is assessed under its own duty rules. The exemption for the SMSF deed does not remove those requirements.
An instrument amending the provisions governing a complying superannuation fund is exempt from Victorian duty under the Duties Act 2000 (Vic) s 39. The exemption also covers a fund that, in the trustees’ opinion, will become a complying superannuation fund within 12 months after execution.
A Legal Consolidated SMSF Deed Update satisfying those requirements does not require stamping merely because it updates the fund’s rules. Separate property transfers have their own duty requirements.
A Legal Consolidated SMSF Deed Update that varies only the fund’s general terms and conditions does not attract Queensland transfer duty and does not require stamping. Queensland Revenue Office expressly confirms this treatment for variations confined to general trust terms.
A cash contribution or cash benefit payment does not, by itself, attract Queensland transfer duty. A separate transaction involving dutiable property, such as Queensland land, requires its own assessment of duty, exemptions and concessions.
See Duties Act 2001 (Qld) ss 8–10 and the Queensland Revenue Office guidance on trusts.
A Legal Consolidated SMSF Deed Update confined to updating the fund’s governing rules, without a dutiable transaction, does not attract WA transfer duty or require lodgement for stamping.
RevenueWA’s superannuation guidance distinguishes the fund deed and its amendments from a duty-endorsed property acquisition or declaration of trust. It requests stamped copies of fund deeds and amendments where they are dated before 1 July 2008.
A separate transfer of dutiable property or declaration of trust over that property has its own duty and lodgement requirements. See Duties Act 2008 (WA) ss 11 and 23 and RevenueWA’s superannuation duty requirements.
Legal Consolidated’s SMSF Update is carefully crafted to update the fund’s governing rules without transferring its assets. A rules-only variation that does not create or vary beneficial interests in trust property is covered by the Stamp Duties Act 1923 (SA) s 71(5)(i), where the original trust instrument is duly stamped. General exemption 30 in sch 2 pt 2 also covers deeds for which no specific charge or basis for charging duty is fixed.
A rules-only update satisfying the applicable exemption does not require lodgement for duty assessment. A separate arrangement that transfers property or creates or varies beneficial interests in South Australian property needs its own duty review before signing.
A Legal Consolidated SMSF Deed Update confined to the fund’s governing rules does not attract ACT conveyance duty or require duty lodgement merely because the rules are updated. The applicable legislation is the current Duties Act 1999 (ACT), ch 2.
A separate transfer of dutiable property or declaration of trust over that property has its own duty requirements.
Superannuation trust deeds and variations dated on or after 1 July 2017 do not require stamping in Tasmania. This applies to a Legal Consolidated SMSF Deed Update signed on or after that date.
Historical deeds dated before 1 July 2017 have different stamping requirements. A separate transaction involving dutiable property also needs its own duty review. See the State Revenue Office Tasmania guidance, paragraph 1.3.
Practical legal strategies from a national tax and superannuation law firm.
Join PRUDENCE